August brought a clear pullback in sales, and inventory moved in the opposite direction. Here is what the latest housing data means for your inspection operation.
Per the National Association of Realtors (NAR), existing home sales totaled 363,000 in August, down -9.5% from a revised July figure of 401,000 (up from the initially reported 400,000) and down -3.5% year over year compared to August 2025’s 376,000. The seasonally adjusted annualized rate (SAAR) came in at 3.98 million, down -2.0% from July’s 4.06 million and down -1.2% versus a year ago.
Supply grew as sales slowed. NAR counted 1.62 million units of housing inventory in August, or 4.9 months of supply, up +3.2% from July and up +5.9% year over year. Zillow tracked 1.41 million active listings, up +0.2% from July and up +3.0% year over year. More homes on the market alongside fewer closings suggests buyers are taking their time.
National median pricing came in at $429,100, up +1.6% year over year, marking the 38th consecutive month of annual price gains.
On the financing side, Fannie Mae continues to project 30-year mortgage rates averaging 6.5% in 2026 and 6.7% in 2027, unchanged from last month. The Mortgage Bankers Association (MBA) now projects rates averaging 6.8% in 2026, up from last month’s 6.7% estimate, and 6.7% in 2027. NAR’s sales forecast is unchanged and isn’t due for its next quarterly update until October.
Current Forecasts
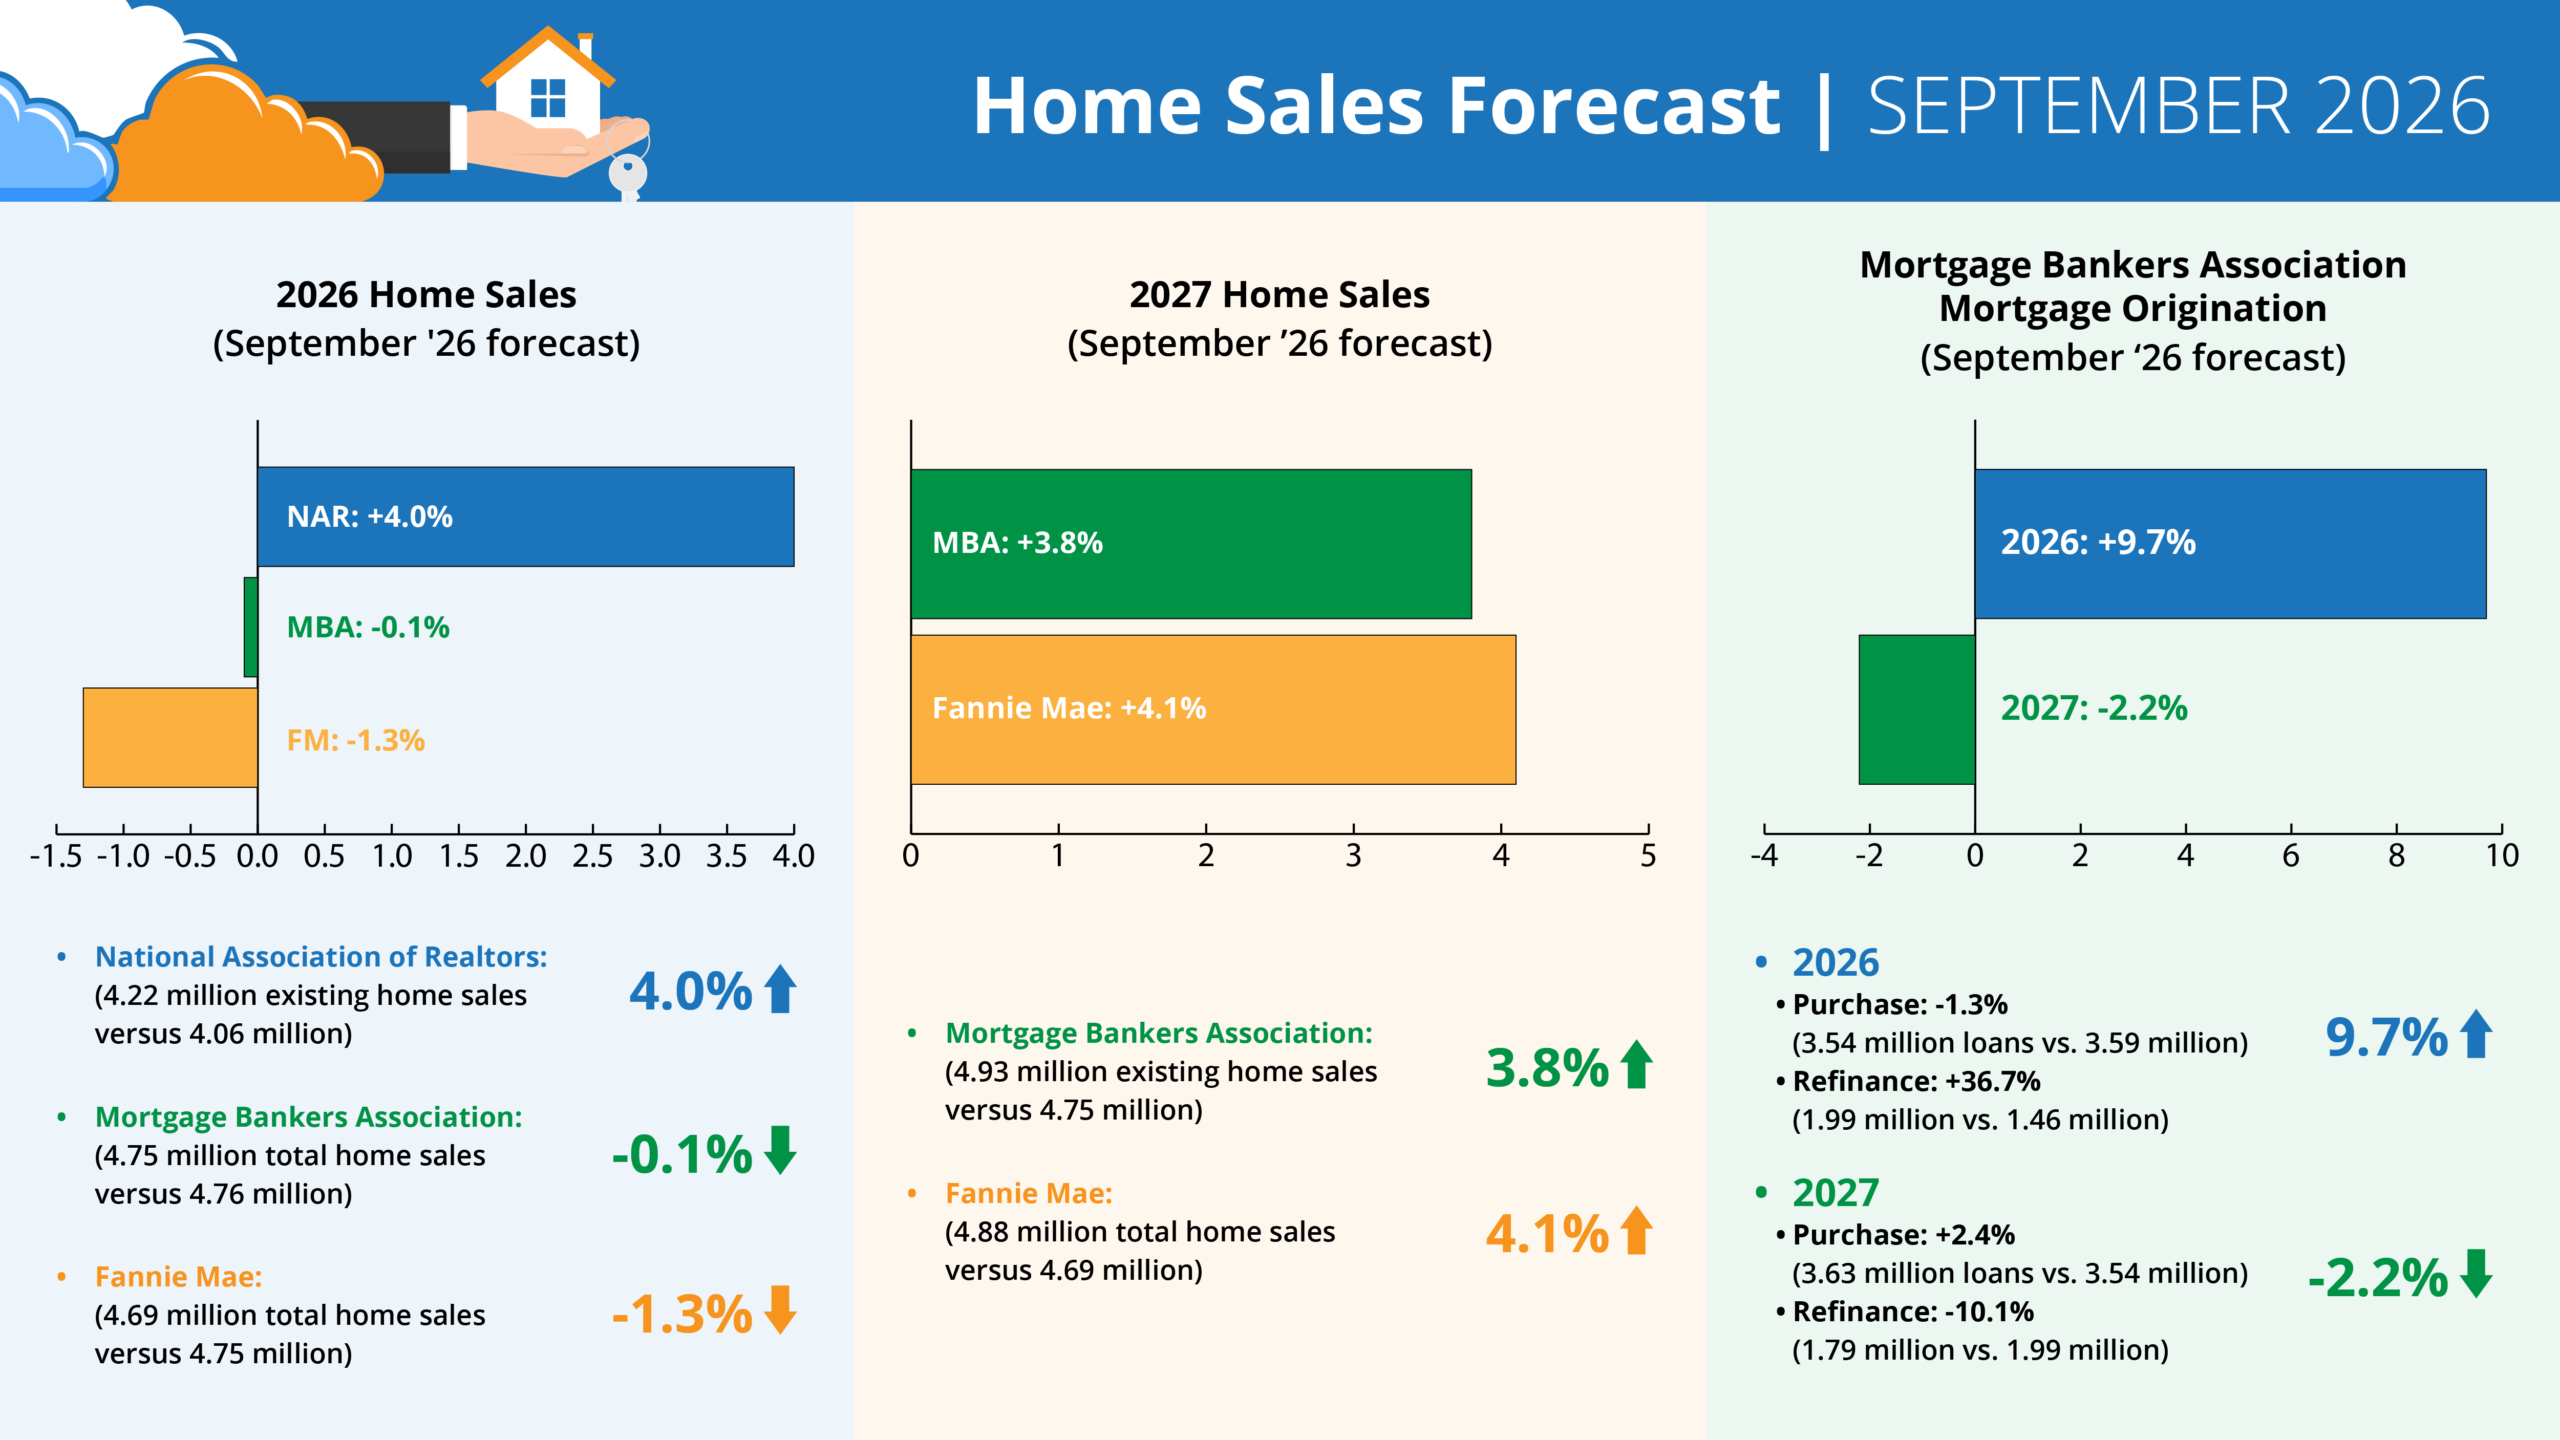
Forecasts for 2026 Home Sales (September ’26 forecast)
- NAR: +4.0% (4.22 million existing home sales vs. 4.06 million), revised April 2026
- MBA: -0.1% (4.75 million total home sales vs. 4.76 million)
- Fannie Mae: -1.3% (4.69 million total home sales vs. 4.75 million)
Forecasts for 2027 Home Sales (September ’26 forecast)
- MBA: +3.8% (4.93 million total home sales vs. 4.75 million)
- Fannie Mae: +4.1% (4.88 million total home sales vs. 4.69 million)
MBA Forecast for Mortgage Originations (September ’26 forecast)
- 2026 Total Mortgage Originations: +9.7% (5.53 million loans vs. 5.04 million)
- Purchase: -1.3% (3.54 million loans vs. 3.59 million)
- Refi: +36.7% (1.99 million vs. 1.46 million)
- 2027 Total Mortgage Originations: -2.2% (5.41 million loans vs. 5.53 million)
- Purchase: +2.4% (3.63 million loans vs. 3.54 million)
- Refi: -10.1% (1.79 million vs. 1.99 million)
Bottom line for multi-inspector teams
The data points to a market that is softening heading into fall. Sales fell sharply from July, inventory kept building, and both MBA and Fannie Mae trimmed their 2026 sales outlooks. That combination calls for careful scheduling and capacity planning rather than adding headcount.
With more listings to choose from, buyers may take longer to commit, which can stretch out the timeline between listing and inspection. Meanwhile, the MBA still projects refi originations to climb +36.7% in 2026 while purchase originations slip. Teams with flexible routing and clear communication will be best positioned to handle whatever mix of purchase and refi-driven inspections comes their way.