If you’ve been wondering whether the fall slowdown is real or just a feeling, the latest housing forecast numbers have some answers for inspectors trying to make sense of an up and down demand for home inspections.
The market is catching its breath, and with mortgage rates still climbing, key forecasters don’t expect it to speed back up anytime soon. Here’s a look at what the latest data says and what it could mean for you, the home inspector.
Let’s start with sales. The National Association of Realtors (NAR) says 341,000 existing homes changed hands in September. That’s down -4.7% from August’s revised 358,000 (first reported at 363,000) and down -3.9% from the 355,000 that closed in September 2025.
There’s a bright spot hiding in the adjusted numbers, though. The seasonally adjusted annualized rate (SAAR), which evens out the usual seasonal ups and downs so you can compare one month to the next, came in at 3.99 million. That’s up +1.5% from August’s revised 3.93 million (revised from 3.98 million), even though it’s still down -2.2% from a year ago.
In other words, the market isn’t falling off a cliff, but it isn’t running at last year’s pace either.
Meanwhile, more houses are sitting out there waiting for buyers. NAR counted 1.6 million homes for sale in September, which works out to 4.8 months of supply. That’s up +1.9% from August and up +4.6% from a year ago.
Meanwhile, Zillow tracked 1.39 million active listings, down -1.5% from August, but its data lines up with NAR on the bigger picture, with listings up +2.5% from last year. What does that mean? Well, put yourself in a buyer’s shoes. More choices and nobody breathing down your neck to make a decision usually means taking your time before making an offer.
As for prices, well, they’re still climbing, just with less pep. The national median price landed at $417,500, up +1.3% from a year ago. That’s 39 months in a row of year-over-year gains, although the gains have been getting smaller.
Then there’s the number that’s weighing on everybody: Mortgage rates. Fannie Mae now expects 30-year rates to average 6.7% in 2026, up from 6.5% last month, and 7.5% in 2027, up from 6.7%.
The Mortgage Bankers Association (MBA) is even more pessimistic about this year, projecting 7.3% in 2026, up from last month’s 6.8%, and 7.1% in 2027, up from 6.7%. Rates are also what pushed NAR Chief Economist Lawrence Yun to cut his 2026 sales outlook to growth of roughly 2% or less, down from the 4% he was predicting back in April. His reasoning? Rates have stayed above 7% since late September.
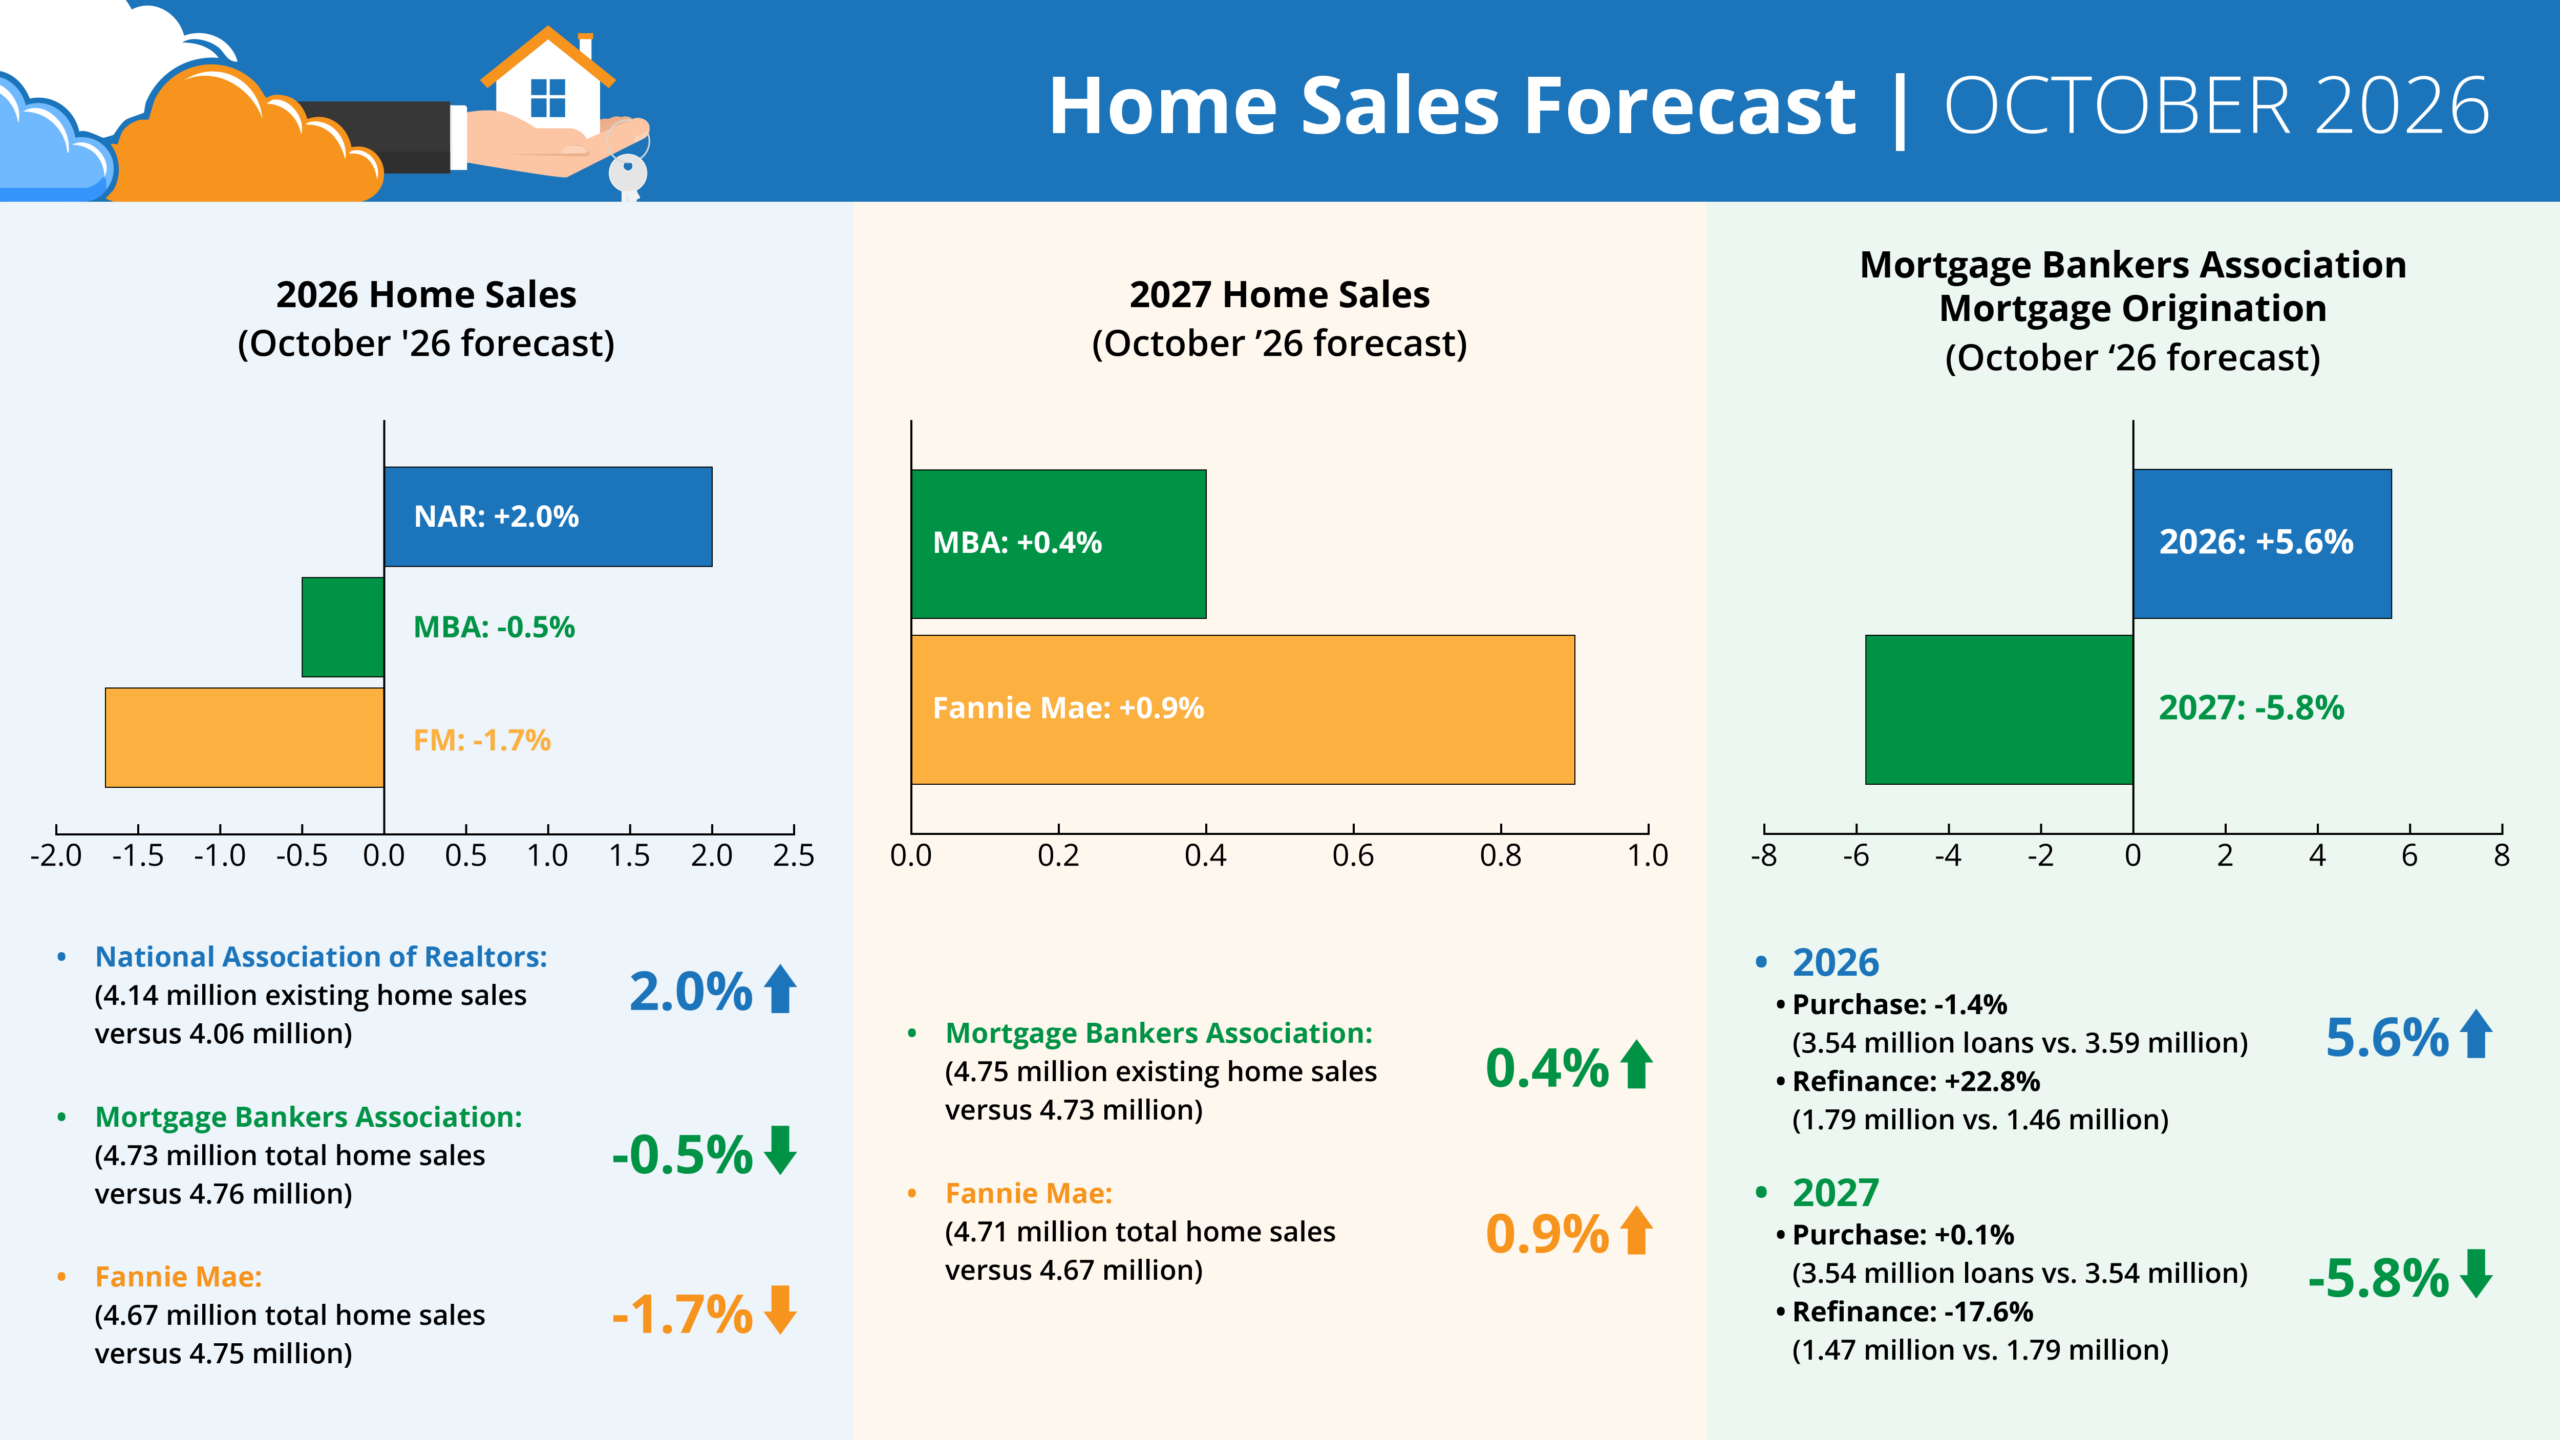
Current Forecasts
Forecasts for 2026 Home Sales (October ’26 forecast)
- NAR: +2.0% (4.14 million existing home sales vs. 4.06 million), revised October 2026
- MBA: -0.5% (4.73 million total home sales vs. 4.76 million)
- Fannie Mae: -1.7% (4.67 million total home sales vs. 4.75 million)
Forecasts for 2027 Home Sales (October ’26 forecast)
- MBA: +0.4% (4.75 million total home sales vs. 4.73 million)
- Fannie Mae: +0.9% (4.71 million total home sales vs. 4.67 million)
MBA Forecast for Mortgage Originations (October ’26 forecast)
- 2026 Total Mortgage Originations: +5.6% (5.32 million loans vs. 5.04 million)
- Purchase: -1.4% (3.54 million loans vs. 3.59 million)
- Refi: +22.8% (1.79 million vs. 1.46 million)
- 2027 Total Mortgage Originations: -5.8% (5.01 million loans vs. 5.32 million)
- Purchase: +0.1% (3.54 million loans vs. 3.54 million)
- Refi: -17.6% (1.47 million vs. 1.79 million)
Bottom line for home inspectors
Here’s how we read it. Higher borrowing costs are putting pressure on the market, and the forecasters see it too: NAR, MBA and Fannie Mae all lowered their 2026 sales outlooks. But the adjusted sales pace ticked up in September, so this looks more like a market taking a breather than one shutting down. That’s your cue to plan carefully, tighten up your scheduling, and hold off on adding headcount until the picture gets clearer.
Think about what’s happening on the buyer’s side. They’ve got more homes to pick from and a bigger monthly payment to worry about, so they’re likely to take longer to commit. That can stretch out the gap between a listing going live and the phone ringing at your office.
There’s some good news on the other side of the ledger, though. MBA still expects refinance originations to jump +22.8% in 2026 while purchase loans slip -1.4%. That refi growth is well below last month’s +36.7% forecast, but it could mean the mix of work coming through the door may look different than it did a year ago. Inspectors with flexible schedules and clear communication will be the ones who handle that mix without scrambling.
Looking for home inspection software to power your business? Start your free 30-day trial and see for yourself, or learn more about the ISN Report Writer and our business management features.